Due Diligence After the Deal: What Entrepreneurs Should Verify Before Operating an Acquired Company
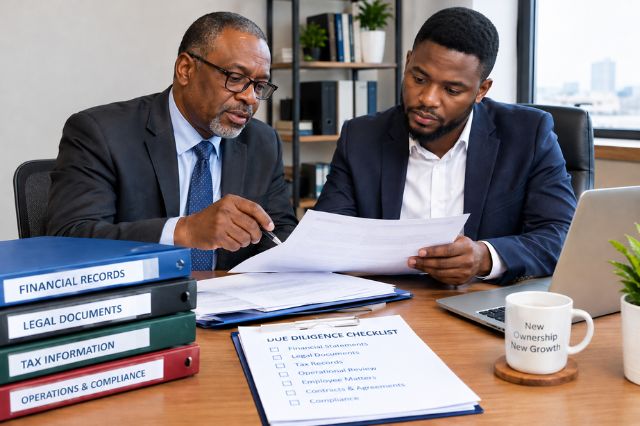
Closing the transaction is not the same as finishing the transition
Entrepreneurs often treat the closing date as the finish line of an acquisition. The ownership documents are signed, the consideration is paid, and control of the company changes hands. Legally, that may complete the transaction. Operationally, however, it is usually the beginning of a second phase.
An acquired company already has a history. It may have existing state filings, bank relationships, tax accounts, insurance policies, licenses, contracts, vendors, employee records, software access, and internal documents created under prior ownership. Some of those records update automatically when ownership changes. Many do not.
That creates a practical risk for the new owner. The company can be validly transferred while different systems still describe different versions of the business. A state record may show an old address. A bank may still recognize a prior signer. A vendor may have outdated billing contacts. A license may still name a former responsible individual.
Post-closing due diligence is the process of reconciling those differences before they become operational problems.
1. Confirm exactly what changed at closing
Begin with the transaction itself. The new owner should be able to explain, in plain language, what was transferred and on what date.
Was the transaction a purchase of stock or membership interests, or was it an asset purchase? Who owned the company immediately before closing, and who owns it now? Were new directors, officers, managers, or authorized signers appointed? Did the legal entity remain the same, or was a new entity created to acquire the assets?
These questions matter because the answers determine which records should change and which should remain historical.
The closing file should contain the signed purchase agreement, assignments or transfer documents, board or member approvals where applicable, updated ownership ledgers or schedules, and any resolutions establishing new authority. If those documents disagree on dates, ownership percentages, titles, or signing authority, resolve the inconsistency before using them with banks, regulators, vendors, or future counterparties.
2. Reconcile state records with the post-closing reality
Next, review the business registry in the company’s formation state and in other states it is registered to do business.
Confirm the legal name, entity type, status, principal office, mailing address, registered agent, and any publicly listed managers or officers. Determine whether amendments, statements of information, annual reports, or foreign-registration updates are required because of the ownership or management change.
A certificate of good standing can be useful evidence that certain filing obligations are current. However, this is not a complete health report for the company. It does not normally tell a buyer whether contracts are assignable, taxes are fully resolved, licenses remain valid, or internal ownership records are accurate.
The state registry should therefore be treated as an independent checkpoint that must agree with the company’s internal records, not as a substitute for the rest of the review.
3. Verify banking authority before moving money
Banking problems after an acquisition are especially disruptive because they can affect payroll, vendor payments, deposits, and day-to-day liquidity.
The new owner should confirm which accounts belong to the company, who currently has online access, who is authorized to sign, what payment methods are active, and whether prior owners or employees still have credentials.
Banks may require updated beneficial-ownership information, resolutions, identification, corporate documents, or other evidence before changing signers or access permissions. Those requirements vary by institution, so the safest approach is to contact each bank directly rather than assume that a private ownership transfer automatically updates the account.
Review ACH permissions, wire templates, debit cards, check stock, remote-deposit access, recurring payments, and any treasury-management services. Remove obsolete authority only after confirming that required replacement access is functioning.
4. Make tax administration part of the handoff
Tax accounts should be reviewed early because ownership changes can affect responsible-party information, payroll administration, state accounts, and sometimes the need for a new employer identification number.
The IRS explains that whether a business needs a new EIN depends on the type of entity and the nature of the ownership or structural change. A new owner should not assume that the existing EIN always continues or that a new one is always required.
Review federal and state tax registrations, payroll-tax accounts, sales-tax permits, prior filing obligations, and the address to which government notices are sent. Identify who has access to online tax portals and who is authorized to speak with tax agencies.
This is also the right time to confirm that the company’s accountant or tax professional understands the effective date and structure of the acquisition.
5. Audit licenses, permits, and regulated activities
A company may legally exist while still lacking a license required for a particular activity, location, or owner.
Create an inventory of every material license and permit used by the business. For each one, determine whether it belongs to the entity, a location, or an individual; whether the ownership change triggers notice or reapplication; and whether the business activity after the acquisition remains within the approved scope.
Do the same for professional credentials, local permits, industry registrations, and foreign qualifications.
This review is especially important when the new owner plans to change the company’s product line, geographic footprint, staffing model, or industry classification. A license that was adequate for the seller’s operations may not cover the buyer’s intended activity.
Also read: A Complete Guide to Mastering Business Acumen and Entrepreneurial Success
6. Review contracts for change-of-control and assignment issues
An acquisition does not automatically make every contract portable.
Review customer agreements, leases, equipment financing, software subscriptions, vendor contracts, distribution agreements, insurance policies, and other material commitments. Look for assignment restrictions, change-of-control clauses, notice requirements, renewal dates, personal guarantees, and termination rights.
For each agreement, classify the required action: no change, notification, consent, amendment, replacement, or professional review.
This exercise also helps identify obligations that may not have been obvious during the closing process, such as minimum purchase commitments, auto-renewing subscriptions, deposits, maintenance agreements, or personal guarantees that need to be released or replaced.
7. Secure digital access and institutional knowledge
Modern businesses can be disrupted by lost passwords just as easily as by missing legal documents.
Prepare a complete inventory of critical systems: business email, domain registrar, website hosting, cloud storage, accounting software, payroll, CRM, merchant processing, banking portals, social accounts, advertising platforms, phone systems, and vendor dashboards.
Confirm that the company—not a former employee’s personal email address—controls the recovery information for important accounts. Update administrators, passwords, multifactor-authentication devices, billing contacts, and recovery methods.
At the same time, capture institutional knowledge that may never appear in formal records. Ask who approves refunds, how recurring reports are produced, which vendors are critical, where renewal dates are tracked, and what processes depend on a particular employee’s memory.
The goal is not merely to gain login access. It is to make sure the new owner can operate the company without relying on undocumented knowledge held by the seller.
8. Reconcile employees, payroll, and internal authority
If the acquired company has employees, verify the systems that determine who gets paid, who approves time, who can change compensation, and who has access to employee information.
Review payroll-provider access, timekeeping systems, benefit administration, workers’ compensation information, employee handbooks, leave balances, and manager permissions. Confirm that supervisors know who has authority after the transition.
Employment and payroll obligations are highly fact-specific, so legal, HR, and payroll professionals should be involved where necessary. The operational objective is simpler: the company should be able to pay employees accurately and on time while maintaining clear control over sensitive personnel systems.
Also read: Top Tips for Payroll Success
9. Build a 30-day reconciliation list
One of the easiest ways to control the post-acquisition period is to convert the review into a short reconciliation list.
For every important business fact or relationship, identify four things: the current record, the desired post-closing state, the person responsible for the update, and the deadline.
Useful categories include ownership, officers and managers, addresses, registered agent, banking, tax accounts, licenses, insurance, contracts, payroll, merchant processing, vendors, software access, domain ownership, and corporate records.
Label each item as complete, pending, blocked, or not applicable. Attach supporting evidence when a task is completed.
This creates a visible operating record instead of relying on memory or a chain of emails.
10. Distinguish historical facts from current business strength
Entrepreneurs acquiring an older entity should also be careful not to confuse corporate history with current business quality.
The formation date is a historical fact. It can provide useful context, but it does not prove that the company is profitable, creditworthy, compliant, or likely to receive financing.
Lenders, suppliers, insurers, and other counterparties can consider current financial statements, payment history, cash flow, debt, guarantees, industry conditions, management, collateral, and many other factors.
The same discipline used in operational due diligence should therefore be applied to financial expectations: verify the current facts instead of relying on assumptions created by the company’s age.
The goal is an operating company that can prove its current reality
A successful acquisition should leave the new owner with more than signed closing documents. It should leave the business in a state where its records, accounts, permissions, and operating relationships consistently describe the company that exists today.
That consistency has practical value. It makes it easier to answer questions from banks, accountants, insurers, employees, vendors, licensing agencies, and future investors or buyers.
The post-closing period is therefore not administrative cleanup. It is part of the acquisition itself.
Entrepreneurs who treat the first several weeks as a structured verification project are more likely to discover mismatches while they are still easy to correct. Instead of repeatedly reconstructing the transaction each time someone asks a question, they create a reliable operating record that can support the business going forward.
Disclosure: The author works with Wholesale Shelf Corporations. This article is educational and does not constitute legal, tax, accounting, lending, or financial advice.